Making tax digital sole traders need to know one thing above all else: it’s your gross income that counts, not your profit — and that catches a lot of people out. Here’s exactly how the thresholds work, and the specific situations that trip up sole traders in particular.
The three thresholds
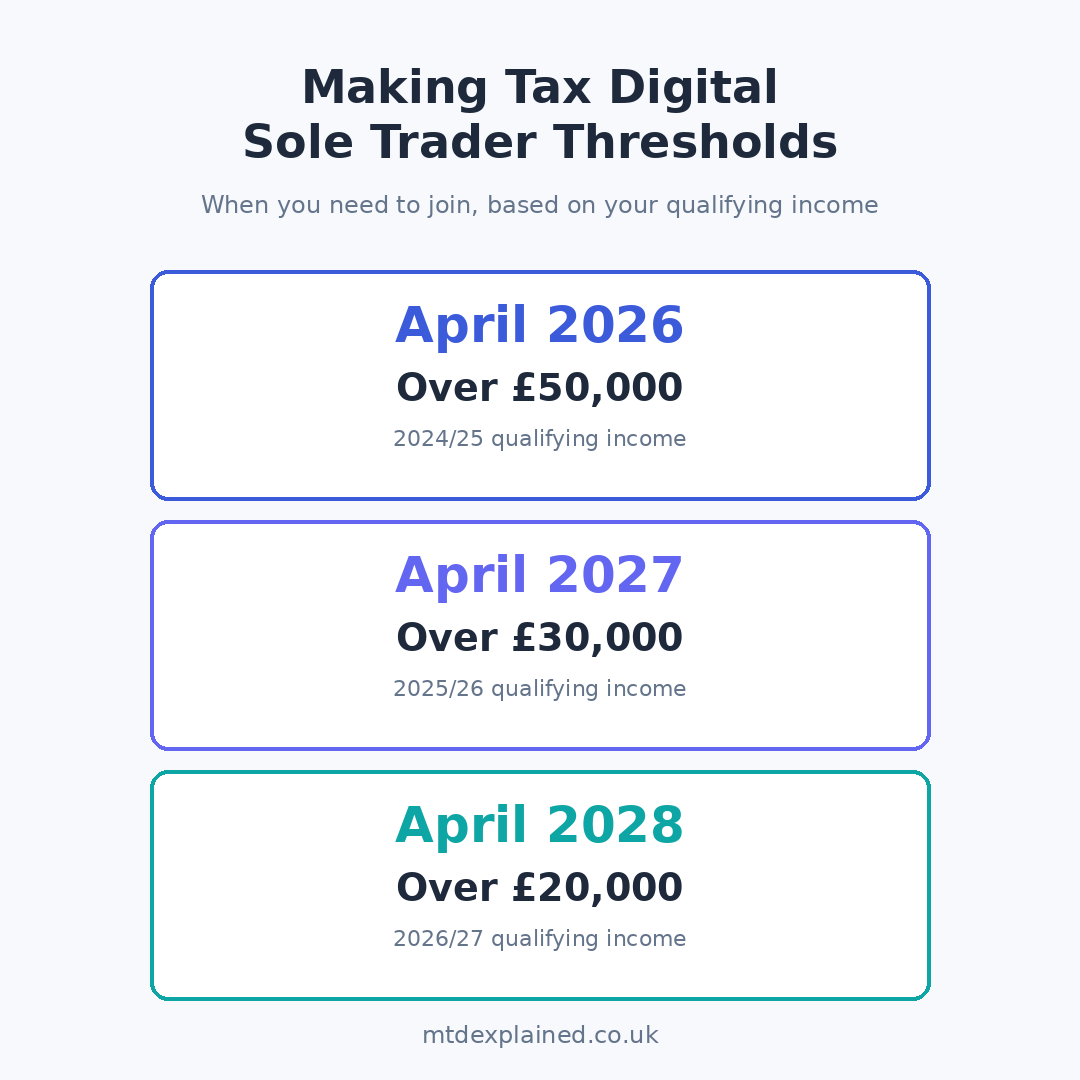
- From 6 April 2026 — if your gross income from self-employment and/or property was over £50,000 in the 2024/25 tax year, you need to join.
- From 6 April 2027 — the threshold drops to £30,000, based on your 2025/26 income.
- From 6 April 2028 — it drops again to £20,000, based on your 2026/27 income.
Your start date depends on the income you earned in the relevant prior tax year, not what you’re earning now. If you’re currently below the threshold but expect to cross it later, you’ll simply be brought in at that later phase.
It’s turnover, not profit — and this genuinely surprises people
This is the biggest trap for sole traders specifically. Your “qualifying income” is your gross turnover — the total money coming into the business before you deduct any expenses, stock costs, or allowances. It is not your taxable profit.
So if your business brings in £58,000 in sales but your actual profit after expenses is only £34,000, it’s the £58,000 figure that gets checked against the threshold — not the £34,000. Plenty of sole traders assume they’re safely under because their profit is modest, only to find their turnover puts them straight into MTD.
Running more than one sole trader business?
If you have more than one sole trader business — say, a tradesperson who also sells goods online under a different name — HMRC adds the qualifying income from all of them together. You can’t treat each business separately to stay under the threshold; it’s your combined trading income that counts.
Importantly, once you are in MTD, you still submit separate quarterly updates for each business — the combined figure only decides whether you’re in the system, not how you report once you’re there.
Side income and small side hustles
If you’re employed but also run a small side business, that self-employment income still counts towards your qualifying income — even if it’s not your main source of income. The test HMRC uses is simply whether the income needs to go on a Self Assessment return, not how significant it is to you personally.
There’s one useful exception: HMRC’s £1,000 trading allowance means you don’t need to report self-employment income under £1,000 on a Self Assessment return at all — so very small, occasional side income can sit outside MTD entirely. But be careful: if your turnover is already above the threshold, you can’t use the £1,000 allowance to bring yourself back under it. The allowance only helps if your income genuinely is that low to begin with.
Sole trader income plus a rental property
If you’re self-employed and also a landlord, HMRC combines your self-employment turnover and your gross rental income to test against the threshold. So a sole trader earning £32,000 and receiving £22,000 in rent has combined qualifying income of £54,000 — over the Phase 1 threshold, even though neither figure alone reaches £50,000.
(This is general guidance, not personalised advice — if you’re unsure how your specific situation is assessed, HMRC’s own online checker or a qualified accountant can confirm your exact position.)
Leave a Reply